

India is reshaping the global fintech landscape through scale, innovation and Digital Public Infrastructure (DPI). The introduction of Aadhaar, expansion of internet connectivity and development of Unified Payments Interface (UPI) transformed financial services. These innovations enabled digital identity, instant payments and consent-based data sharing at population scale. India’s experience demonstrates how technology can make financial services more accessible, efficient and inclusive.
This transformation has positioned India as a global centre for fintech innovation and digital finance. The Global Fintech Fest (GFF) 2026 reflects India’s growing global influence in this sector. The 7th edition of GFF is being held in Mumbai from 8 to 11 September 2026. It provides a platform for global dialogue, collaboration and innovation in financial technology.
Since its inception in 2020, GFF has grown into one of the world’s leading fintech gatherings. Its growth reflects increasing global interest in India’s digital financial architecture and fintech capabilities.

Institutions Driving the Success of GFF 2026
Payments Council of India (PCI), National Payments Corporation of India (NPCI) and Fintech Convergence Council (FCC) are the principal organizers of GFF. Additionally, GFF 2026 is supported by:
- Ministry of Electronics and Information Technology (MeitY)
- Department of Financial Services, Ministry of Finance
- New, Emerging and Strategic Technology (NEST) Division, Ministry of External Affairs
- NITI Aayog
- Reserve Bank of India (RBI)
- Securities and Exchange Board of India (SEBI)
- International Financial Services Centres Authority (IFSCA)
- Pension Fund Regulatory and Development Authority (PFRDA)
GFF 2026 - Powering the Next Wave of Financial Innovation
The 7th Global Fintech Fest 2026 is far more than a conference. It is the world's largest fintech festival, uniting the brightest minds to shape an AI-powered future. Every edition of the GFF journey has been driven by innovation and a shared vision of inclusive growth and prosperity.
Global Fintech Fest - Theme & Agenda
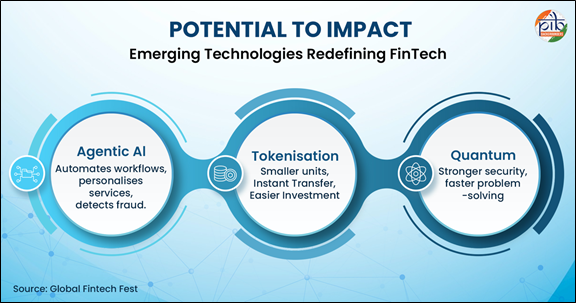
The theme of GFF 2026 is “Potential to Impact: Agentic AI | Tokenisation | Quantum: Trusted, Connected, Global Systems for Inclusive Finance.” It is built upon three foundational technologies that are shifting the landscape of global finance toward autonomous, programmable, and secure ecosystems.
Agentic AI: It enables financial systems to sense, decide, and act in real time within strong governance frameworks. It orchestrates end-to-end workflows, strengthens regulatory oversight, enhances fraud prevention, and responsibly personalizes financial services at scale while empowering human decision-making through explainable intelligence.
Tokenisation: It transforms assets into programmable digital units, enabling fractional ownership, instant settlement, and interoperable money. By unlocking liquidity and democratising access, it reshapes capital markets, payments, and participation across global financial systems.
Quantum: Quantum technologies introduce a foundational shift in computation and security. From quantum-safe cryptography to advanced risk optimization, they strengthen systemic resilience and ensure long-term trust in the financial infrastructure of tomorrow.
- PhonePe X Visa Collaboration
- PhonePe and Visa unveiled three new payment solutions — Tap to Pay, Cross Border Scan to Pay and Smart Accept, aimed at enabling cardless payments for consumers and card acceptance for micro-merchants. The partnership also brings together Visa’s online tokenisation, contactless payments and cross-border QR capabilities on the PhonePe platform, making it the first Indian app to offer the combined suite.
- Amazon Pay's Smart Wallet
- Amazon Pay launched Smart Wallet, enabling AI agents to make UPI payments on behalf of users, initially for flight ticket bookings. The company has also introduced biometric authentication through the wallet and offline tap-to-pay, with plans to expand agentic UPI payments to more merchants and use cases.
- NPCI's FiMI Banking
- NPCI unveiled FiMI Banking, India’s first sovereign compact AI model designed specifically for Indian retail banking use cases. NPCI will collaborate with HDFC Bank to further develop the model, while also open-sourcing its banking AI benchmarks, technical report and evaluation sets to help assess AI agents on safety, actions and response appropriateness.
- Multicurrency Forex Services on Bharat Connect
- RBI Deputy Governor Rohit Jain announced the soft launch of multicurrency forex services on Bharat Connect, adding five currencies — euro, pound, Canadian dollar, Swiss franc and UAE dirham, to the platform. The offering, being tested through a controlled user group, enables foreign currency purchase, overseas remittances and forex card reloads through participating banks and digital channels.
- The RBI and SEBI launched a Demat 2.0 pilot at the Global Fintech Fest 2026 to test tokenisation of corporate bonds using Distributed Ledger Technology (DLT). The first phase covered three issuers, while the next phase will focus on secondary-market trading.
- Demat 2.0 is the new market infrastructure developed to test a new way of issuing, holding, trading and settling corporate bonds. The bond is created as a digital token on a distributed ledger, a shared electronic record maintained simultaneously by market infrastructure institutions using Distributed Ledger Technology (DLT). The ledger is owned by the depositories.
- Demat 2.0 is connected to RBI’s wholesale CBDC (e₹) through the Unified Market Interface (UMI) of RBI. This enables atomic settlement, i.e., the bond and the money move instantaneously. Thus, the technology improves the efficiency of transactions in the securities market.
- Asset servicing, including interest payments and redemption, can be handled automatically through smart contracts, i.e., instructions written into the ledger that execute on their own.
Understanding Fintech
FinTech is generally described as an industry that leverages technology to make financial systems and the delivery of financial services more efficient. It refers to “technologically enabled financial innovation” that can lead to new business models, applications, processes or products, with a significant impact on financial markets, institutions and the provision of financial services.
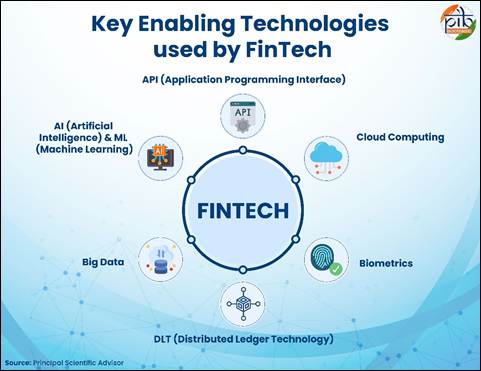
Key Enabling Technologies in FinTech
- Application Programming Interface (API): APIs are a set of rules and protocols that enable different software applications to communicate with each other. They allow developers to build new financial applications and services by integrating existing platforms.
- Cloud Computing: Cloud computing uses online networks of computing resources to provide scalable and flexible digital infrastructure. It reduces operational costs and enables financial institutions to handle large volumes of data efficiently.
- Biometric Technology: Biometrics uses unique and measurable human characteristics, such as fingerprints and facial recognition, for identification and authentication. It improves security and enables easier access to financial services.
- Distributed Ledger Technology (DLT): DLT is a digital record-keeping system where transaction data is stored across multiple locations simultaneously. It enhances transparency, security and efficiency in financial transactions.
- Big Data Analytics: Big Data refers to large volumes of structured and unstructured data that can be collected, analysed and utilised through digital tools. It helps financial institutions improve decision-making, risk assessment and customer services.
- Artificial Intelligence (AI) and Machine Learning (ML): AI and ML systems enable computers to perform tasks requiring human-like intelligence. Machine learning allows systems to learn from data and improve performance without direct human programming.
Importance & Benefits of Fintech
FinTech has the ability to reshape the financial landscape in a fundamental way - offering consumers a wider choice of financial products at more competitive prices, while helping financial institutions operate more efficiently. FinTech is delivering measurable gains in efficiency, inclusion and financial stability across economies.
- FinTech has played a key role in making the financial sector more efficient. For example, UPI, recognised by the IMF as the world's largest real-time payment system, processed 2,365.8 crore transactions worth ₹29.88 lakh crore in July 2026 alone, with 741 banks live on the platform - transaction volumes have grown nearly 12,000-fold since FY 2016–17.
- By overcoming market failures such as information asymmetry or high transaction costs, FinTech helps enhance financial inclusion. India’s Financial Inclusion Index increased from 43.4 in March 2017 to 70.0 in March 2026.
- The growth of FinTech is diversifying credit sources beyond traditional banking channels. Greater diversity in credit provision can reduce systemic risks arising from dependence on a limited number of banks. This can strengthen the resilience, competition and stability of the financial ecosystem.
The Foundation of India's FinTech Success
India’s FinTech success is built on a decade of investment in Digital India and DPI. This foundation combines universal access, digital identity, interoperable payments and open digital networks. These capabilities have created an ecosystem where financial innovation can scale rapidly and inclusively.
JAM Trinity: The Jan Dhan–Aadhaar–Mobile (JAM) Trinity provides the foundation for digital financial inclusion. Jan Dhan accounts provide access to formal banking, while Aadhaar enables secure digital identity. Expanding internet access connects citizens to digital financial services.
- As of 26th August 2026, 59.15 crore Jan Dhan accounts had been opened and Aadhaar enrolments crossed 144 crore by March 2026. It has created a large, accessible base for fintech services across the country.
UPI: Unified Payments Interface (UPI) provides the interoperable payment infrastructure powering India’s digital transactions.
- UPI transactions reached 24,509 million in August 2026.
- The platform handles nearly 50% of global real-time digital transaction volume and operates in 11 countries.
- This open infrastructure allows fintech firms to build innovative payment solutions at population scale.
Digital Identity and Documents: Trusted digital identity is essential for secure and efficient financial services. Aadhaar e-KYC enables digital customer verification while reducing paperwork and onboarding time.
- It has processed more than 2,458 crore transactions as of 29 June 2026.
- DigiLocker has over 73.53 crore registered users and has issued 936.03 crore documents.
- These digital systems strengthen trust while simplifying customer onboarding and verification across financial services.
Digital Welfare Delivery: Direct Benefit Transfer (DBT) uses digital financial infrastructure to transfer benefits directly into beneficiaries’ bank accounts.
- This reduces intermediaries, improves transparency and supports faster delivery of government benefits.
- Cumulative DBT transfers reached ₹53.26 lakh crore as of September 2026.
- Such large-scale digital transfers demonstrate the capacity of India’s financial infrastructure to deliver services efficiently.
Open Digital Commerce: Open Network for Digital Commerce (ONDC) extends India’s interoperable digital approach beyond payments.
- By June 2026, ONDC had reached over 20 crore buyers and 5 lakh sellers across 1,000+ cities.
- Its Financial Services category is creating additional opportunities for digital financial products.
- This open architecture can help fintech firms reach new users and markets more efficiently.
A Robust, Trusted Regulatory Ecosystem
As India's FinTech sector has scaled, the Government and the Reserve Bank of India have continuously strengthened the regulatory and consumer-protection architecture that underpins public trust in digital finance.
- Self-regulation and standards: RBI's Framework for Self-Regulatory Organisation (s) in the FinTech Sector (SRO-FT, May 2024) promotes ethical conduct, market integrity and dispute resolution within the industry.
- Payment security: RBI's Master Directions on Digital Payment Security Controls (2021) mandate common minimum-security standards across various payment channels (including internet and mobile banking) to combat web and mobile app threats, while NPCI has deployed Artificial Intelligence (AI)/Machine Learning (ML) based fraud monitoring for UPI transactions.
- Data protection: The Ministry of Electronics and Information Technology notified the Digital Personal Data Protection Act in 2023 and the Digital Personal Data Protection Rules in 2025 to safeguard the personal data of individuals.
- Safe innovation testing: The Reserve Bank of India introduced the Regulatory Sandbox framework in August 2019, allowing innovative financial products and services to be tested in a controlled regulatory environment, with or without regulatory relaxations.
- Consumer protection in digital lending: A strengthened regulatory framework, a Digital Lending Apps (DLA) directory and cybercrime-reporting mechanisms (the National Cybercrime Reporting Portal at cybercrime.gov.in and Helpline 1930) safeguard citizens against fraudulent lending apps, while the public-facing SACHET portal facilitates complaints specifically regarding the illegal collection of deposits.
The regulatory approach is therefore not limited to responding to innovation after it reaches the market. It creates institutional mechanisms through which responsible innovation can be tested, assessed and supported.
Way Forward
India’s FinTech ecosystem is built on scale, interoperability, innovation and institutional trust. Its Digital Public Infrastructure provides a strong foundation for accessible, affordable and inclusive financial services. The next phase should deepen digital sovereignty, technological self-reliance and responsible innovation. Open digital platforms can further democratise technology for citizens, start-ups and businesses.
Emerging technologies can enable smarter, safer and more efficient financial services. Artificial Intelligence, tokenisation, blockchain and quantum technologies can unlock new opportunities across the financial ecosystem. Strong cybersecurity, data protection and consumer safeguards will remain essential as digital finance expands. FinTech innovation should remain anchored in people-centric governance, inclusion and public value.
India can further share its digital expertise through partnerships with emerging economies and the Global South. This can strengthen India’s role as a trusted partner in building inclusive digital financial systems. The way forward is to build a sovereign, secure and inclusive digital financial ecosystem. This approach can position India as a global leader in shaping the future of people-centric digital finance.
